Tax-Efficient Early Retirement: Roth Conversions and MAGI Playbook
The fastest path to tax-efficient early retirement is a coordinated sequence: live off taxable basis and Roth contributions first, run annual Roth conversions sized to fill low brackets while protecting ACA subsidies, and use SEPP/72(t) only when you need immediate income before Roth ladders mature. A well-executed withdrawal and conversion sequence can reduce federal income tax to near zero in some early retirement years. The mechanics are not complicated, but the order matters enormously.
Highest-impact moves, in priority order:
- Spend taxable basis first. Return of capital is not taxable income. Exhaust cost basis in brokerage accounts before touching gains or retirement accounts.
- Run Roth conversions annually. Fill the 12% bracket (or the 0% long-term capital gains zone) each year during the pre-RMD window. Start five years before you need the converted principal.
- Harvest capital gains at 0%. If your taxable income stays below the 0% long-term capital gains threshold, realized gains cost nothing in federal tax.
- Use SEPP/72(t) only when needed. If you retire before 55 and lack enough taxable savings to bridge five years, SEPP unlocks penalty-free IRA income. The lock-in risk is real; exhaust other options first.
- Maximize HSA distributions for medical costs. Tax-free withdrawals for qualified expenses reduce MAGI pressure elsewhere.
- Watch IRMAA two years out. Medicare surcharges are triggered by income from two years prior. A large conversion today can raise Medicare premiums in year three.
Complex portfolios with high MAGI swings, Medicare/IRMAA exposure, or inherited accounts benefit most from a licensed tax advisor or CFP before executing any conversion or SEPP election.
Pro Tip: Model your MAGI before December 31 each year. A single unexpected capital gains distribution from a mutual fund can push you over an ACA subsidy cliff or into an IRMAA tier, costing thousands more than the tax on the conversion itself.
Key Takeaways
Tax-efficient early retirement requires coordinating Roth conversions, MAGI management, and withdrawal sequencing across the pre-RMD window to minimize lifetime taxes while protecting ACA subsidies and avoiding IRMAA surcharges.
| Point | Details |
|---|---|
| Roth ladder timing | Start conversions five years before you need the principal; each conversion has its own five-year clock. |
| MAGI is the master lever | Every conversion, gain, and distribution affects ACA subsidies and IRMAA; model MAGI before year-end, not after. |
| Spend taxable basis first | Return of capital generates zero taxable income; exhaust cost basis before touching gains or retirement accounts. |
| Pre-RMD window is critical | Converting at low rates from retirement to age 73 can reduce future RMDs and lifetime tax liability materially. |
| Progressiveplanner’s Dual Purpose Strategy™ | Adds an IUL-based income stream outside the MAGI framework, complementing Roth ladders for clients with a multi-decade horizon. |
Table of Contents
- What actually drives your tax bill in early retirement?
- Withdrawal sequencing: which accounts to tap first and why
- How to use Roth conversions tax-efficiently in early retirement
- 72(t) SEPP and other penalty-free access options before age 59½
- How does managing MAGI protect your ACA subsidies?
- When should you claim Social Security in early retirement?
- Required minimum distributions: when do they start and how do you reduce them?
- State taxes: how residency and moving affect your retirement income
- Other tax levers: HSAs, QCDs, credits, and catch-up contributions
- A year-by-year tax-planning checklist for early retirees
- How Progressive Planner’s Dual Purpose Retirement Strategy™ fits this playbook
- Capital gains tax strategies for early retirement asset sales
- How early retirement affects Social Security and Medicare taxation thresholds
- Tax considerations for using HSAs during early retirement
- Estate planning and inherited retirement accounts in early retirement
- What Progressive Planner recommends most often
- A tailored retirement review from Progressive Planner
- Sources
What actually drives your tax bill in early retirement?
Three numbers govern almost everything: Modified Adjusted Gross Income (MAGI), provisional income, and your marginal bracket stack. Get comfortable with all three before you touch a single account.
MAGI is your adjusted gross income plus certain add-backs (student loan interest, IRA deductions, tax-exempt interest). For ACA subsidy purposes, it also includes non-taxable Social Security. For most early retirees, MAGI equals AGI because the add-backs are zero. Every dollar of Roth conversion, realized capital gain, or traditional IRA withdrawal flows directly into MAGI.
Provisional income is the metric the IRS uses to determine how much of your Social Security benefit is taxable. If provisional income exceeds $34,000 (single) or $44,000 (married filing jointly), up to 85% of your Social Security benefit becomes taxable ordinary income.
How income stacks in practice: ordinary income (wages, IRA distributions, conversions) fills the bracket from the bottom. Qualified dividends and long-term capital gains sit on top of ordinary income but are taxed at their own preferential rates.
Sample calculation for a married couple filing jointly:
- $30,000 in taxable brokerage basis withdrawals (return of capital, $0 taxable)
- $20,000 in Roth conversion (ordinary income)
- $10,000 in qualified dividends
- Less: $30,000 standard deduction (2025 figure for married filing jointly)
- Taxable ordinary income: $20,000 minus $30,000 = $0 (fully absorbed by standard deduction)
- Qualified dividends taxed at 0% (income below the 0% LTCG threshold)
The MAGI for ACA purposes is still $50,000 ($20,000 conversion + $10,000 dividends + $20,000 basis withdrawals are not income, but any Social Security would add back in). A couple with $50,000 MAGI and two people on a Marketplace plan may still qualify for meaningful premium tax credits — but a $15,000 larger conversion could push them above 400% of the Federal Poverty Level and eliminate subsidies entirely.
Pro Tip: *MAGI smoothing is the discipline of keeping income within a target band across multiple years. Small income changes near ACA subsidy cliffs or IRMAA tiers have outsized dollar effects.
Withdrawal sequencing: which accounts to tap first and why
The sequence in which you draw income is one of the most powerful tax-efficiency levers in retirement. Most retirees default to the path of least resistance. The optimal path requires a bit more intention.
The practical sequence for early retirees:
-
Roth contributions (always available penalty-free and tax-free, no age restriction)
-
Taxable account basis (return of capital, zero taxable income)
-
Taxable account gains (target the 0% long-term capital gains window)
-
Roth conversion fills (sized to top of 12% bracket or to preserve ACA subsidies)
-
Traditional IRA/401(k) distributions (ordinary income; use when bracket room exists)
-
SEPP/72(t) (last resort before 59½ if taxable savings cannot bridge five years)
-
Estimate annual spending need: $80,000.
-
Pull $40,000 from taxable account basis (zero taxable income).
-
Realize $15,000 in long-term gains from appreciated positions (0% federal rate if income stays below the threshold).
-
Run a $25,000 Roth conversion to fill remaining bracket space.
-
Total MAGI: $40,000 ($15,000 gains + $25,000 conversion). Check against ACA subsidy target.
-
Verify no IRMAA exposure two years forward.
Numbered example with real dollar impact:
A married couple, both 52, spending $85,000 per year. They have $400,000 in taxable basis, $600,000 in a traditional IRA, and $200,000 in Roth contributions.
At $15,000 taxable income, the couple pays roughly $1,500 in federal income tax on $85,000 of spending. Their MAGI of $85,000 keeps them within ACA subsidy range for a family of two.
Pro Tip: Coordinate withdrawals across spouses before year-end. If one spouse has a pension or part-time income, shift Roth conversions to the lower-income spouse’s IRA to keep household MAGI within the target band. Divorce or separation can dramatically change this math; a legal overview of how account division affects RMDs and beneficiary rules is worth reviewing if your situation changes.
How to use Roth conversions tax-efficiently in early retirement
Roth conversions are the central tool of tax-efficient early retirement planning. The logic is simple: pay tax now at a low rate so you never pay tax on that money again.
The five-year rule for converted principal: each Roth conversion starts its own five-year clock. Converted principal cannot be withdrawn penalty-free until five years after the conversion year, even if you are past 59½. This means a Roth ladder requires starting conversions five years before you need the money. If you retire at 50, begin converting in year one so the 2026 conversion is accessible in 2031.
Sample bracket-fill conversion flow (married filing jointly, 2025):
Critical warning callouts:
- IRMAA two-year lookback. Medicare Part B and D surcharges use income from two years prior. A large conversion in 2026 affects 2028 Medicare premiums. Model this before converting above $103,000 MAGI (single) or $206,000 (MFJ) in 2025.
- ACA subsidy cliffs. A conversion that pushes MAGI above 400% of the Federal Poverty Level can eliminate premium tax credits entirely for the year.
- Conversion-tax timing. Tax on conversions is due in the year of conversion. Withhold from non-retirement funds or make estimated quarterly payments to avoid underpayment penalties.
- Form 8606. File this IRS form every year you make a nondeductible IRA contribution or Roth conversion. It is your permanent record of basis and prevents double taxation.
Pro Tip: For high-balance households, paced Roth conversions during low-income years can produce six-figure lifetime tax savings compared with passive decumulation. The math favors converting aggressively in the pre-RMD window, but only up to the point where ACA subsidies and IRMAA thresholds are preserved.
72(t) SEPP and other penalty-free access options before age 59½
Several options exist, each with different trade-offs.
Main penalty-free access methods:
- 72(t) SEPP (Substantially Equal Periodic Payments). Three IRS-approved calculation methods: Required Minimum Distribution method, Fixed Amortization, and Fixed Annuitization. The RMD method produces the lowest annual payment and recalculates each year. Amortization and Annuitization produce higher, fixed payments. SEPP requires strict adherence; altering the schedule retroactively triggers the 10% penalty plus interest on all prior distributions.
- Rule of 55. Applies only to 401(k) plans from the employer you left at age 55 or older. Does not apply to IRAs. More flexible than SEPP because there is no lock-in period.
- Roth conversion ladder. Convert traditional IRA funds to Roth each year; access converted principal five years later, penalty-free. Requires a five-year taxable bridge. Usually the most flexible option for those who can fund the bridge.
- 457(b) plans. Governmental 457(b) accounts have no 10% penalty for withdrawals at any age after separation from service. A significant advantage for former government employees.
- Public safety / age-50 exceptions. Qualified public safety employees (police, firefighters, EMS) can access 401(k) funds penalty-free at 50. A narrow but valuable exception.
- HSA reimbursements. Medical expenses paid out of pocket in any prior year can be reimbursed from an HSA at any time, tax-free. Stockpiling receipts creates a flexible, penalty-free income source.
Flexibility and risk comparison:
The Roth ladder is usually more flexible than SEPP for those who can bridge five years with taxable savings. SEPP makes sense only when immediate, guaranteed income is required and the retiree accepts the lock-in risk. Once a SEPP schedule is set, it runs until you reach 59½ or five years have passed, whichever is later. Modifying it — even once — triggers penalties on every prior distribution.
Calculation note: the three SEPP methods use your account balance and an IRS-approved interest rate. An exact calculation requires your specific balance, age, and the current IRS-published interest rate. A fee-only financial planner or tax advisor can run these numbers precisely before you commit.
Pro Tip: Never start a SEPP without documented calculations from a qualified advisor and a written record of the method chosen. The IRS has ruled against taxpayers who could not prove their calculation method. Keep the documentation permanently.
How does managing MAGI protect your ACA subsidies?
ACA premium tax credits are calculated directly from MAGI. Large Roth conversions or realized capital gains can push MAGI above subsidy thresholds and sharply increase net healthcare costs. For many early retirees, protecting ACA subsidies saves more money than the tax benefit of a larger conversion.
Enhanced subsidies enacted through the American Rescue Plan and extended through 2025 soften the cliff somewhat, but state-level variation and plan-year changes mean the threshold can shift. Check Healthcare.gov for current FPL tables and your state’s specific rules.
Scenario: two MAGI outcomes for a couple, age 52, two people on a Marketplace plan:
- MAGI $65,000 (within subsidy range): estimated monthly premium after credit, roughly $400–$600 depending on plan and state.
- MAGI $90,000 (above 400% FPL for a family of two): full unsubsidized premium, potentially $1,200–$1,800 per month. The difference can exceed $10,000 per year.
The net effect is negative $9,000.
Practical checklist for testing ACA plan quotes at projected MAGI:
- Estimate projected MAGI for the year: add all income sources (conversions, gains, dividends, Social Security).
- Look up the current FPL for your household size at Healthcare.gov.
- Calculate your MAGI as a percentage of FPL.
- Get plan quotes at your projected MAGI on Healthcare.gov or your state exchange.
- Run the same quote at MAGI $5,000 higher and $5,000 lower to identify cliff proximity.
- If a conversion would push you over a cliff, reduce the conversion to stay below the threshold.
Managing MAGI to protect subsidies can save more than the tax cost of a conservative Roth conversion. The subsidy math often dominates the tax math for early retirees in the $50,000–$100,000 MAGI range. Run both calculations before finalizing any conversion amount.
Pro Tip: Balance conversions with capital gains harvesting. This fills two tax-efficiency goals simultaneously without doubling your MAGI impact.
When should you claim Social Security in early retirement?
Social Security timing is a tax decision as much as a longevity decision. But the tax implications of a larger benefit later are real.
Claiming age comparison:
- Claim at 62: reduced benefit (up to 30% less than full retirement age benefit). Lower provisional income in early years, which may preserve ACA subsidies and keep Roth conversion room open. Smaller benefit means less Social Security taxed later.
- Claim at full retirement age (66–67, depending on birth year): full benefit. Provisional income rises, potentially pushing more of the benefit into the 85% taxable zone.
- Claim at 70: maximum benefit, up to 32% more than full retirement age. Higher provisional income in later years can push more Social Security into taxable territory and interact with IRMAA thresholds.
How Social Security interacts with Roth conversions: every dollar of Roth conversion increases provisional income. This is a hidden tax cost of conversions that many retirees miss.
Decision checklist for Social Security timing:
- Estimate your life expectancy honestly. The break-even age for delaying from 62 to 70 is typically around 80–82.
- Assess your portfolio size. If you have enough taxable and Roth assets to fund spending without Social Security, delaying costs nothing in liquidity.
- Check your replacement income sources. A pension or part-time income may make early Social Security unnecessary.
- Model the bracket effect. Run your projected MAGI with and without Social Security at each claiming age to see the tax cost of a larger benefit.
- Consider spousal benefits. A higher-earning spouse delaying to 70 maximizes the survivor benefit, which is a tax-efficient estate move.
Pro Tip: Delaying Social Security while running Roth conversions in low-income years is one of the most tax-efficient sequences available. You pay tax on conversions at low rates now, then receive a larger, partially tax-free Social Security benefit later — with a smaller traditional IRA balance generating lower RMDs.
Required minimum distributions: when do they start and how do you reduce them?
RMDs are the IRS’s mechanism for collecting deferred taxes on traditional retirement accounts. Under current law (SECURE 2.0), RMDs begin at age 73 for most taxpayers.
The pre-RMD window between early retirement and age 73 is the single most valuable tax-planning period for large traditional account holders. Converting during this window at low marginal rates prevents those balances from compounding into larger RMDs that force income into higher brackets later.
Model example: the cost of not converting:
A retiree at 55 with $1.2 million in a traditional IRA who does no conversions might face RMDs starting at 73 of $50,000–$70,000 per year, depending on account growth.
Pre-RMD conversion pacing:
These figures are illustrative. Actual amounts depend on account balances, other income, and bracket thresholds in each year.
Pro Tip: Multi-year conversion pacing requires watching IRMAA two years forward at every step. Converting $60,000 at 66 affects Medicare premiums at 68. Build a simple spreadsheet that tracks projected MAGI, IRMAA tier, and ACA status for each year from retirement to age 75. Adjust conversions annually based on actual income, not just the original plan.
State taxes: how residency and moving affect your retirement income
For early retirees with flexibility, residency is a lever worth pulling.
State-level checklist:
- Does your state tax Social Security? Roughly a dozen states tax Social Security benefits to some degree. Moving before you claim can eliminate that liability.
- Does your state tax pension and retirement account income? Some states exempt pension income entirely; others tax IRA and 401(k) withdrawals as ordinary income.
- What are the residency tests? Most states use a combination of domicile (intent) and physical presence (183-day rule). Establishing domicile in a new state requires more than just spending time there.
- Part-year residency traps. If you move mid-year, both states may claim the right to tax income earned while you were a resident. A large Roth conversion in the year of a move can be taxed by two states.
Common scenarios:
- Move before a big conversion. If you plan a large conversion, completing the move and establishing domicile in a no-income-tax state before the conversion year saves state tax on the entire converted amount.
- Domicile timing rules. Some states (California, New York) aggressively audit departing residents. Keep records of the move date, voter registration change, driver’s license update, and primary home sale.
- States with retirement income exemptions. Several states exempt military pensions, public pensions, or a portion of all retirement income. The exemption amounts vary and change with legislation.
Practical next steps:
- Pull your state’s current tax treatment of Social Security, pensions, and IRA withdrawals from the state revenue department website.
- Estimate your annual state tax bill under current residency and under two alternative states.
- Factor in cost of living, property taxes, and healthcare access. A state with no income tax but high property taxes may not produce net savings.
- If the move pencils out, time it before any large conversion or asset sale.
Pro Tip: California’s “clawback” rules can tax income earned before you left if you maintain any California connections (rental property, business interest, or even a storage unit). Sever all ties cleanly before the tax year of a large conversion.
Other tax levers: HSAs, QCDs, credits, and catch-up contributions
Several smaller tools can move the needle significantly, especially in the years just before Medicare eligibility.
Health Savings Accounts (HSAs):
An HSA is the only account with a triple tax benefit: contributions are deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. To contribute, you must be enrolled in a High-Deductible Health Plan (HDHP). Once you enroll in Medicare, contributions stop. The strategy for early retirees is to contribute the maximum each year while on an HDHP, pay medical costs out of pocket, and let the HSA compound. After 65, HSA funds can be withdrawn for any purpose (taxed as ordinary income, like a traditional IRA), but qualified medical withdrawals remain tax-free at any age.
Qualified Charitable Distributions (QCDs):
QCDs allow IRA owners age 70½ or older to transfer up to $105,000 directly to a qualified charity. The transfer counts toward the RMD but is excluded from taxable income. This is more tax-efficient than taking the RMD and then donating, because the QCD never enters AGI. For early retirees, QCDs become relevant in the RMD years, but planning for them now (identifying charitable goals, keeping traditional IRA balances available) is worthwhile.
Catch-up contributions:
If you are still working in your 50s, the IRS allows catch-up contributions to 401(k) plans ($7,500 extra above the standard limit in 2025) and IRAs ($1,000 extra). SECURE 2.0 introduced enhanced catch-up contributions for ages 60–63 in 401(k) plans. These reduce taxable income now and build the tax-deferred balance you will later convert.
Tax credits for lower-income retirees:
The Retirement Savings Contributions Credit (Saver’s Credit) applies to lower-income taxpayers who contribute to retirement accounts. If your MAGI is low enough in early retirement and you are still making IRA contributions, this credit can offset tax directly. Credits beat deductions dollar-for-dollar.
Pro Tip: Stockpile HSA receipts from every medical expense you pay out of pocket. There is no deadline for reimbursement. A $30,000 accumulation of receipts over ten years becomes a $30,000 tax-free withdrawal you can take at any time, for any reason, as long as the expenses were qualified when incurred.
A year-by-year tax-planning checklist for early retirees
Tax-efficient early retirement is not a one-time decision. It is an annual process of modeling, adjusting, and executing. The ten-year pre-RMD window is where the most value is created.
Sample withdrawal and conversion schedule (married couple, retire at 52, $1.5M traditional IRA, $400K taxable, $200K Roth contributions):
These figures are illustrative. Actual amounts depend on spending needs, account balances, and annual bracket thresholds.
Worksheet fields to track annually:
- Projected annual spending (after-tax)
- Taxable basis available (cost basis in brokerage accounts)
- Planned Roth conversion amount
- Projected MAGI (sum of all income sources)
- Expected ACA subsidy at projected MAGI (check Healthcare.gov)
- IRMAA exposure two years forward
- State tax liability at projected income
- HSA contribution and balance
- Roth conversion ladder status (which years’ conversions are accessible)
- Traditional IRA balance (to project future RMDs)
Annual planning steps:
- Pull prior-year tax return and update all account balances in January.
- Estimate spending for the current year.
- Model Roth conversion amount against current bracket thresholds and ACA subsidy cliff.
- Check IRMAA exposure for two years forward.
- Execute conversions by December 31 (no extensions for conversion timing).
- Harvest capital gains in taxable accounts if income stays below 0% LTCG threshold.
- Maximize HSA contribution if on an HDHP.
- File Form 8606 with your tax return.
Pro Tip: Run a mid-year check in June or July. Unexpected capital gains distributions from mutual funds, a part-time consulting payment, or a property sale can change your MAGI projection significantly. Adjust conversions downward before year-end if income has already risen.
How Progressive Planner’s Dual Purpose Retirement Strategy™ fits this playbook
The playbook above covers the standard toolkit: Roth ladders, MAGI management, SEPP, and sequencing. Progressive Planner’s Dual Purpose Retirement Strategy™ adds a complementary layer that addresses a gap the standard toolkit leaves open: the risk that a long retirement depletes tax-deferred accounts faster than conversions can keep pace, or that market downturns compress the taxable buffer at the worst possible time.
How the strategy works in practice:
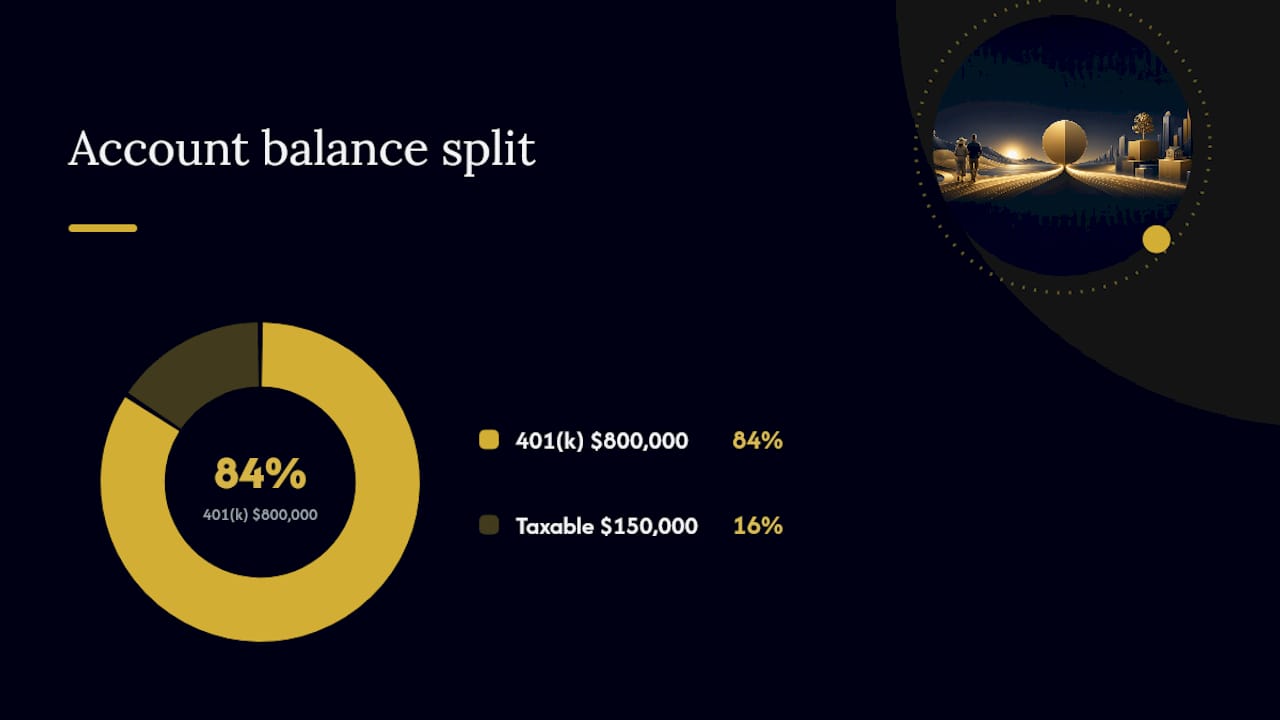
A client couple, both 50, with $800,000 in a 401(k) and $150,000 in taxable savings, begins the standard Roth ladder. Simultaneously, they redirect a portion of annual savings into an Indexed Universal Life (IUL) policy. The IUL builds cash value linked to a market index with downside protection. That cash value becomes a second tax-advantaged income stream, accessible without triggering MAGI, without affecting ACA subsidies, and without adding to provisional income for Social Security taxation purposes.
Risks and benefits for early retirees:
- Tax benefit: IUL policy loans are generally not taxable income and do not affect MAGI, which preserves ACA subsidies and avoids IRMAA triggers.
- Liquidity: cash value access typically requires the policy to have been funded for several years. This is not a short-term liquidity tool.
- Fees: IUL policies carry internal costs (cost of insurance, administrative charges) that reduce net returns compared with a pure investment account. These costs must be modeled against the tax benefit.
- Death benefit / estate: the death benefit passes income-tax-free to beneficiaries, which can be a meaningful estate planning tool alongside inherited IRA planning.
- Downside protection: the index-linked crediting with a floor (typically 0%) means the cash value does not lose value in a down market year, unlike a taxable brokerage account.
What to expect from a Progressive Planner consultation: a discovery session covers your account inventory, current MAGI, projected spending, and existing insurance coverage. The advisor models Roth conversion scenarios, Medicare/IRMAA stress tests, and an IUL illustration alongside your existing plan. You receive a side-by-side income comparison showing projected outcomes with and without the Dual Purpose layer.
Pro Tip: Bring your last two tax returns, a current account statement for every retirement account, and your most recent Social Security statement to the consultation. The more complete the picture, the more precise the modeling.
Capital gains tax strategies for early retirement asset sales
Unlike tax-loss harvesting (selling losers to offset gains), tax-gain harvesting resets your cost basis upward at zero tax cost. If you later sell the same position, you owe tax only on gains above the new, higher basis.
Practical steps:
- Identify positions with large unrealized long-term gains in your taxable account.
- Calculate your projected taxable income for the year, including any Roth conversions.
- Determine how much room remains below the 0% LTCG threshold.
- Sell appreciated positions up to that room, then immediately repurchase if you want to maintain the position. (The wash-sale rule does not apply to gains, only losses.)
- Document the sale and repurchase dates and new cost basis.
Asset location matters too. Vanguard’s institutional guidance identifies asset location as a core tax-efficiency lever alongside sequencing.
How early retirement affects Social Security and Medicare taxation thresholds
Retiring early changes the Social Security and Medicare tax picture in two distinct ways: it reduces your future Social Security benefit (because you accumulate fewer high-earning years in the calculation), and it creates a multi-year window where your income is low enough to avoid Medicare IRMAA surcharges entirely.
Social Security benefit reduction: the Social Security Administration calculates your benefit using your 35 highest-earning years. Retiring at 50 instead of 62 leaves up to 12 years of potential high-earning years replaced by zeros. This can reduce your projected benefit meaningfully. Check your Social Security statement at SSA.gov for your current projected benefit at each claiming age.
Medicare IRMAA: Medicare Part B and D premiums include income-related surcharges (IRMAA) for higher-income beneficiaries. The surcharge is based on income from two years prior. Early retirees who keep MAGI low during the pre-Medicare years arrive at Medicare enrollment with no IRMAA exposure. A large conversion in the year before Medicare eligibility can trigger surcharges in the first year of coverage.
The Medicare enrollment timing trap: if you retire before 65 and lose employer coverage, you must find alternative coverage (ACA Marketplace, COBRA, or a spouse’s plan). This penalty applies for life.
Tax considerations for using HSAs during early retirement
The HSA’s triple tax advantage makes it the most tax-efficient account in the retirement toolkit, but the rules governing early retirement use are specific.
Contribution eligibility: you can contribute to an HSA only while enrolled in a qualifying HDHP. For 2025, the contribution limit is $4,300 for self-only coverage and $8,550 for family coverage, plus a $1,000 catch-up for those 55 and older. Once you enroll in Medicare (typically at 65), contributions stop. Enrolling in Medicare Part A retroactively (which can happen if you claim Social Security before 65) can create an inadvertent excess contribution problem.
Withdrawal rules: HSA withdrawals for qualified medical expenses are tax-free at any age. After 65, non-medical withdrawals are taxed as ordinary income only, with no penalty, making the HSA function like a traditional IRA for non-medical spending.
The stockpiling strategy: pay all medical costs out of pocket during early retirement, keep every receipt, and let the HSA compound tax-free. Years later, reimburse yourself for those documented expenses with a tax-free HSA withdrawal. There is no time limit on reimbursement as long as the expense was incurred after the HSA was established.
MAGI impact: HSA contributions made through payroll are excluded from MAGI entirely. Contributions made directly (not through payroll) are deductible above the line, reducing AGI and MAGI. HSA withdrawals for qualified expenses do not appear in income at all. This makes the HSA one of the few tools that reduces MAGI while providing spending power.
Estate planning and inherited retirement accounts in early retirement
Early retirees who inherit retirement accounts face a compressed tax timeline under current law. The SECURE Act (2019) and SECURE 2.0 eliminated the “stretch IRA” for most non-spouse beneficiaries, replacing it with a 10-year rule: inherited traditional IRA funds must be fully distributed within 10 years of the original owner’s death.
Tax impact for early retirees who inherit: if you inherit a large traditional IRA at 50, you must distribute the entire balance by age 60. Depending on your income in those years, distributions could push you into higher brackets, eliminate ACA subsidies, and trigger IRMAA. Planning the distribution schedule across the 10-year window to minimize bracket impact is critical.
Spousal inherited accounts: a surviving spouse has more options. They can roll the inherited IRA into their own IRA, treat it as their own, or remain a beneficiary. Rolling into their own IRA delays RMDs until the surviving spouse’s own RMD age (73 under current law), which is usually the better tax outcome.
Estate planning implications for your own accounts: naming beneficiaries correctly on retirement accounts avoids probate and controls the tax outcome for heirs. A Roth IRA inherited by a non-spouse beneficiary still requires distribution within 10 years, but those distributions are tax-free. Converting traditional IRA funds to Roth during your lifetime passes a tax-free asset to heirs rather than a fully taxable one. Divorce or changes in family structure can affect beneficiary designations significantly; a legal review of how divorce affects retirement account division and beneficiary rules is worth completing after any major life change.
Per-stirpes vs. per-capita designations: naming beneficiaries with a per-stirpes designation ensures that if a primary beneficiary predeceases you, their share passes to their children rather than being redistributed among surviving beneficiaries. This matters for estate tax planning and for preserving the 10-year distribution window for each beneficiary’s share.
What Progressive Planner recommends most often
The most common recommendation from this practice is not the most complex strategy. It is the most disciplined one: build a five-year taxable buffer before you retire, start Roth conversions in year one, and protect ACA subsidies above everything else until Medicare eligibility.
Roth ladders fit the majority of early retirees who have at least $200,000–$300,000 in taxable savings and a traditional IRA or 401(k) they can convert gradually. The math is straightforward, the flexibility is high, and the long-term tax benefit is well-documented. SEPP is the right tool for a narrower group: those who retire before 55, lack a taxable bridge, and need guaranteed income immediately. The lock-in is a real constraint, and most clients who explore SEPP end up finding a way to avoid it once they see the flexibility cost.
The IUL-based Dual Purpose layer fits clients who have already optimized the standard playbook and want a second income stream that operates entirely outside the MAGI framework. It is not the right first move for someone still building their taxable buffer. It is a strong second move for clients with stable cash flow, a multi-decade time horizon, and a desire to reduce dependence on market performance for retirement income.
One caution worth stating plainly: every projection in this article uses illustrative numbers. Your actual tax outcome depends on your specific account balances, income sources, state of residence, health status, and the tax law in effect each year. Run your own numbers, or have an advisor run them, before executing any conversion, SEPP election, or IUL purchase.
A tailored retirement review from Progressive Planner
Most early retirees have the right instincts but the wrong sequence. A free retirement income review from Progressive Planner covers the four areas where sequencing errors cost the most: account inventory and MAGI baseline, Roth conversion scenario modeling, Medicare/IRMAA stress testing, and ACA subsidy impact analysis.

What to bring: your last two federal tax returns, current balances for every retirement and taxable account, your most recent Social Security statement from SSA.gov, and a rough estimate of annual spending in retirement. The review takes roughly 60–90 minutes and produces a side-by-side income projection comparing your current trajectory with the Dual Purpose Retirement Strategy™ layered in.
The next step is straightforward: schedule a no-obligation consultation at Progressiveplanner. If the modeling suggests a licensed tax advisor or CPA should be involved in your conversion planning, the review will flag that directly. The goal is a plan you can execute with confidence, not a product sale.
Sources
Save copies of Form 8606 permanently. Check IRS.gov, SSA.gov, and Healthcare.gov annually for updated thresholds; bracket cutoffs, FPL tables, and IRMAA tiers change each year.
- Tax Efficient Retirement Plan Strategies - Vanguard
- Taxes in Early Retirement | White Coat Investor
- Tax tips after you retire | TurboTax
This article provides general educational information about tax strategies and is not a substitute for personalized tax, legal, or financial advice. Consult a licensed tax advisor or CFP before implementing any withdrawal, conversion, or insurance strategy.